Most people searching for a mortgage broker have a home loan in mind. But if you are buying a shop, an industrial unit or an investment building, the lending works quite differently, and the adviser you choose matters.
This guide explains the difference between a commercial mortgage broker and a residential mortgage broker in NZ. It covers lender criteria, documentation and security, so you can approach the right adviser from day one.
What Does a Residential Mortgage Broker Do?
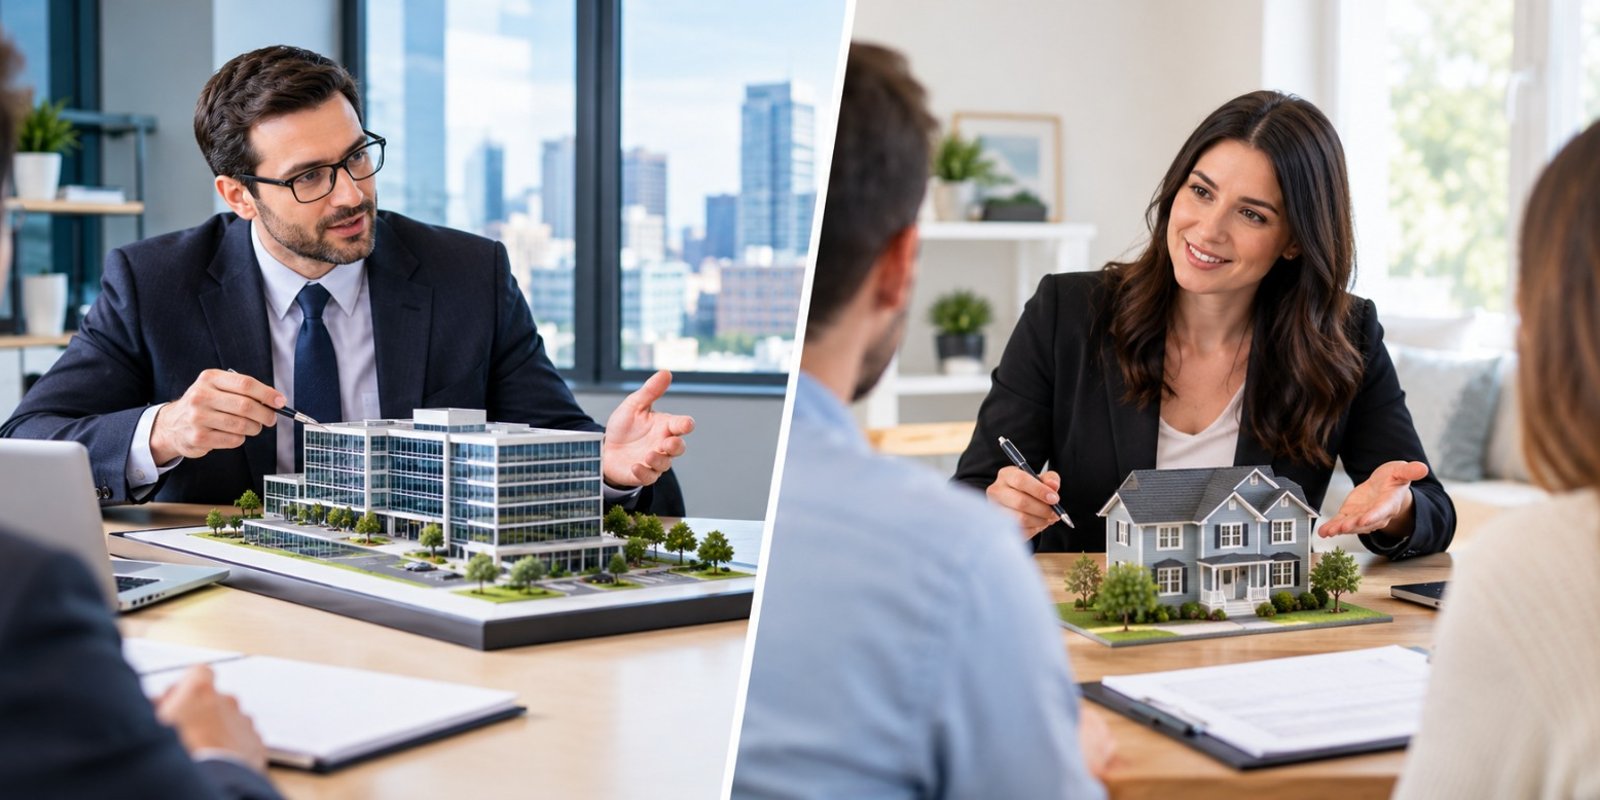
A residential broker helps individuals and families with loans secured over a home. That includes first home loans, refinancing, top-ups and residential investment purchases. Typical mortgage broker services include comparing lenders, estimating your borrowing power, preparing the application and managing it through to settlement. For a full rundown, see our checklist of what a broker handles.
Residential lenders mainly assess you as a person: your income, living expenses, debts and deposit. Consumer credit rules and Reserve Bank lending settings can also influence how much you can borrow and how large a deposit you need.
What Does a Commercial Mortgage Broker Do?
A commercial mortgage broker arranges finance secured over commercial property such as retail premises, offices, warehouses, mixed-use buildings and larger investment properties. A commercial property mortgage broker also works with business owners buying their own premises, and with investors whose income comes from tenants rather than wages.
Commercial lending is assessed differently. Lenders look closely at the property itself, the lease or rental income, and the strength of the borrowing entity, whether that is a company, a trust or an individual. Some deals also suit non-bank lenders when the timing or structure falls outside a main bank's policy.
Key Differences at a Glance
How income is assessed
Residential lending focuses on your personal income and expenses. Commercial lending looks at rental income, business cash flow, or both.Deposit and loan-to-value ratio (LVR)
Commercial loans commonly need a larger deposit, because lenders usually lend a lower percentage of the property's value.Loan term and structure
Commercial loans often have shorter terms, interest-only periods and a refinance or review point at the end, rather than one long principal and interest term.Documentation
Commercial applications usually add company financials, leases and property details to your personal information.Security
Lenders may ask for personal guarantees from directors, or extra security, alongside the property.Valuation and due diligence
A commercial valuer will typically assess lease terms, tenant quality, zoning and condition, which can take longer than a standard home valuation.
Documents You May Need
Residential Application
- Photo ID and proof of address
- Payslips or income evidence
- Recent bank statements
- Details of debts, credit cards and living expenses
- Evidence of your deposit, including KiwiSaver or savings
Commercial Application
- Company or trust documents and details of directors or trustees
- Two years of financial statements and tax returns for the entity and its owners
- A statement of assets and liabilities
- Lease agreements and a rent schedule for the property
- Property details and, where available, a valuation
- A clear explanation of the purchase and your plan for repaying or refinancing the loan
Which Type of Broker Do You Need?
Buying a home or residential rental in your own name
A residential broker is usually the right fit. If it is an investment, our guide to investment property lending explains how lenders assess it.Buying business premises through your company
Look for a broker with real commercial lending experience.Using home equity as the deposit on a commercial purchase
Both sides matter, so choose an adviser who can structure the residential and commercial loans together.
Finding the Right Adviser Locally
Many borrowers prefer a face-to-face meeting. If you are searching for a mortgage broker Papakura or mortgage brokers South Auckland clients can easily visit, check that they handle the loan type you need and not only home loans. Others prefer a Mortgage broker Auckland NZ with wider metro coverage, while a new zealand mortgage broker may be able to work with you remotely.
When comparing mortgage broker companies, look for independence, a broad lender panel and clear disclosure of how they are paid. Our guides on how to choose the right mortgage broker, choosing an adviser in Papakura and how brokers get paid cover what to check.
Questions to Ask Before You Apply
Any mortgage broker NZ borrowers speak to should be happy to answer these:
- Do you regularly arrange both residential and commercial loans?
- Which lenders can you access for my type of property?
- How are you paid, and will I be charged any fees?
- What will you need from me, and how long will approval take?
- Who will be my day-to-day contact?
This article is general information only and is not personal financial advice.
Not Sure Whether Your Plan Needs Residential or Commercial Finance?
Talk it through with the independent team at Capital Finance. We compare the market for you and explain your options in plain English.
Call 0800 626 685 or contact our team online to get started.
FAQ
Is a commercial mortgage broker more expensive than a residential one?
Fee arrangements vary. Residential brokers are often paid by the lender, while more complex commercial deals may involve fees. Ask for any fees to be explained in writing before you proceed.
Can one broker handle both residential and commercial loans?
Some can, but experience differs. Ask how often they arrange the type of loan you need and which lenders they use for it.
Do commercial property loans need a bigger deposit?
Usually, yes. Lenders commonly lend a lower share of a commercial property's value than a home's, so the deposit or equity required is often higher.
Can I use my home as security for a commercial purchase?
Sometimes. It can reduce the cash deposit you need, but it also puts your home at risk, so get legal and financial advice first.
How long does commercial loan approval take?
Often longer than a home loan, because of commercial valuations, lease reviews and legal due diligence. Timeframes vary by lender and property.